
Last week, I shared how I manage the finances for our two-person, three-cat household. Now for the fun part: the actual breakdown!
Cha-ching!
Where the money goes
Our expenses change from month to month so I’ll give ranges instead of exact figures.
| 🏡 Housing (mortgage, tax, insurance) | $2,300 – $3,300 |
| 💡 Utilities (electricity, water, internet, phone) | $500-600 |
| 🚗 Transportation* (car, gas, maintenance, public transit) | $1,100 – $1,600 |
| 🍜 Food (groceries, restaurants, takeout) | $950 – $1,400 |
| 🧴 Essentials (toiletries, cleaning supplies, batteries, etc.) | $170 – $250 |
| 🐱 Cats | $120 – $180 |
| 💆🏻♀️ Wellness (meds, supplements, massage, dental) | $240 – $350 |
| 📺 Entertainment (subscriptions, movie tickets) | $45 – $65 |
| 🎁 Gifts (this one swings the most, very unpredictable) | $50 – $1,500 |
| 🛍️ Shopping (clothing, shoes, furniture, tech) (also unpredictable) | $100 – $1,100 |
| 📖 Hobbies (journaling, books, hiking, etc.) | $0-600 |
* Starting next month, our monthly transportation costs will dramatically go down from $1,100-1,600 to $450-650 because after seven longgg years, we finally paid up our car loan! 😍
A slice-by-slice look
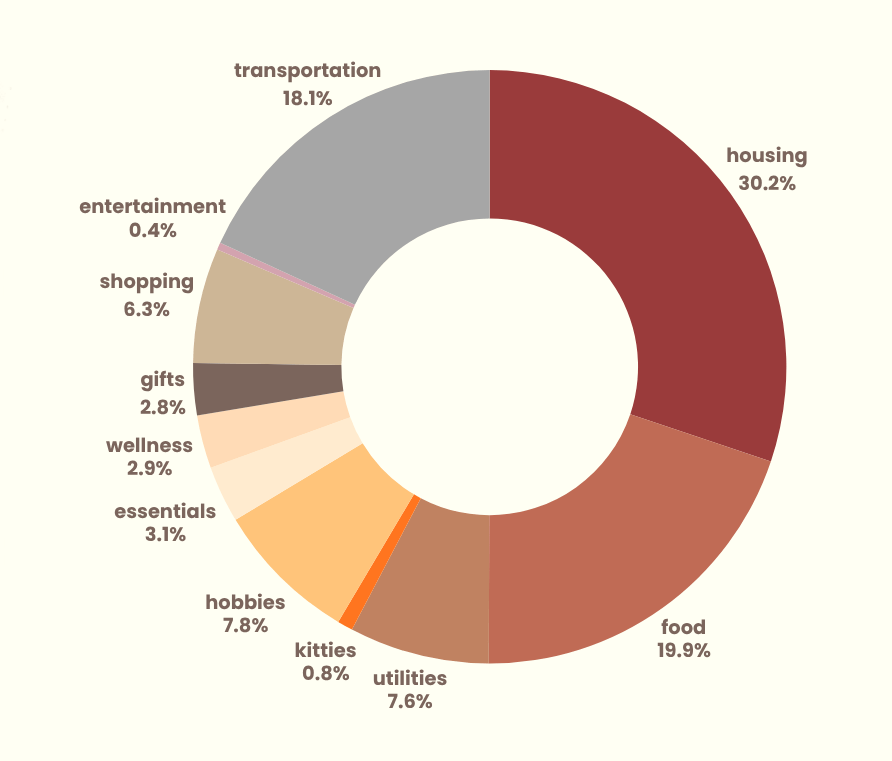
This is how our spending looked like last month:
Money ramblings
Just some random thoughts about all this money stuff.
Renting vs buying a home
Kapag narinig nyo ‘tong line na ‘to: “Magkano ang rent nyo monthly? $1,500? Konti na lang ang idadagdag pambayad nyo na yan ng mortgage!” And they will further explain kung pano “nasasayang” yung pera nyo sa rent versus buying a home na “nakaka-build na sana kayo ng equity”—WAG KAYONG MANIWALA. Looking back, I think people who give that kind of advice is being irresponsible. “Konti” na lang ang idadagdag?? Talaga?!
Unang-una, hindi ba kelangan muna ng downpayment? 5-20% yun ng total price tag ng bahay. San namin yun huhugutin?? May isang nagsabi samin na, “Pwede nyo namang i-loan yung downpayment kung kulang pa yung ipon nyo.” So wala pa kaming mortgage loan, may utang na kami agad??
Pangalwa, bakit nalilimutan nilang banggitin yung property tax, home insurance, at mortgage insurance na kakabit ng pagbili ng bahay? Eh monthly din yun binabayaran! Ang significant kaya ng amount na yun pag idinagdag sa mortgage payments. Nasan dun yung “konti”? Hindi pa nga kasali dyan yung house maintenance costs at association fees eh. Konti?! Kalokohan.
Kaya ito ang mas magandang advice. Bumili kayo ng bahay kapag:
- Meron na kayong 20% na pang-down. I suggest 20% para wala na kayong babayaran na mortgage insurance.
- Do a simple calculation: kung magkano yung monthly rent nyo ngayon, doblehin nyo. Ngayon, kung kaya nyong magbayad ng double your rent, it’s highly likely na hindi kayo mag-s-struggle every month with your housing costs.
If this feels impossible right now, there is absolutely nothing wrong with renting. Kung ako nga lang ang masusunod nagre-rent pa rin kami ngayon eh. Pero dahil napunta na kami dito, might as well share kung ano yung reality and debunk yung mga laos na advice. At this point, I don’t even see owning a house as an investment anymore. In this economy, it’s simply a lifestyle choice.
Open minded ka ba?
Haha kapag kasi naririnig yung word na ‘investing,’ pyramid scheme or scam agad yung unang pumapasok sa isip ng iba. In my world, when I say investing, it’s investing in the stock market. Isa sa mga core principles ko when it comes to personal finance ay regularly investing part of our paycheck in the stock market. This is very important to me. Kapag hindi kami nakakapag-invest, I feel like we are failing financially.
Kaya meron akong bitter emotions nung bumili kami ng bahay kasi simula nung nagka-bahay kami, natigil yung pag-iinvest namin. Kasi hindi namin in-expect na magdodoble pala yung gastos once magka-bahay na kami (gigil nanaman ako dun sa mga nagsabi na konti na lang daw ang idadagdag tss).
Kung hindi kami bumili ng bahay and we continued investing major portions of our paycheck to the stock market, we’d be doing so much better financially. Because according to an article I’ve read, historically speaking, investing in the stock market will give you superior gains (9-11% annually) versus investing in real estate (only 4-6% per year). Now, if you really want to invest in real estate, you can do that without buying a home. Just Google ‘REITs’ and buy some REIT stocks (I like REI-UN.TO and SRU-UN.TO).
Before some of you say, “Hindi ako marunong nyan” or “Nakakatamad” or “Mahirap yan”, investing in the stock market is what helped us save for our 20% downpayment (that’s $104,650!!). Kung makakatulong sya samin financially in a very significant way, bakit ako tatamarin aralin? At hindi ko nga gets pano naging mahirap kasi truthfully, ang boring nya. Every payday, consistently lang kaming bumibili ng XEQT and VUN stocks (since we’re in Canada) and that’s it. Paulit-ulit lang. Hindi ko na kelangan mag-isip. Gusto nyong mag-earn ng passive income? Eto yun.
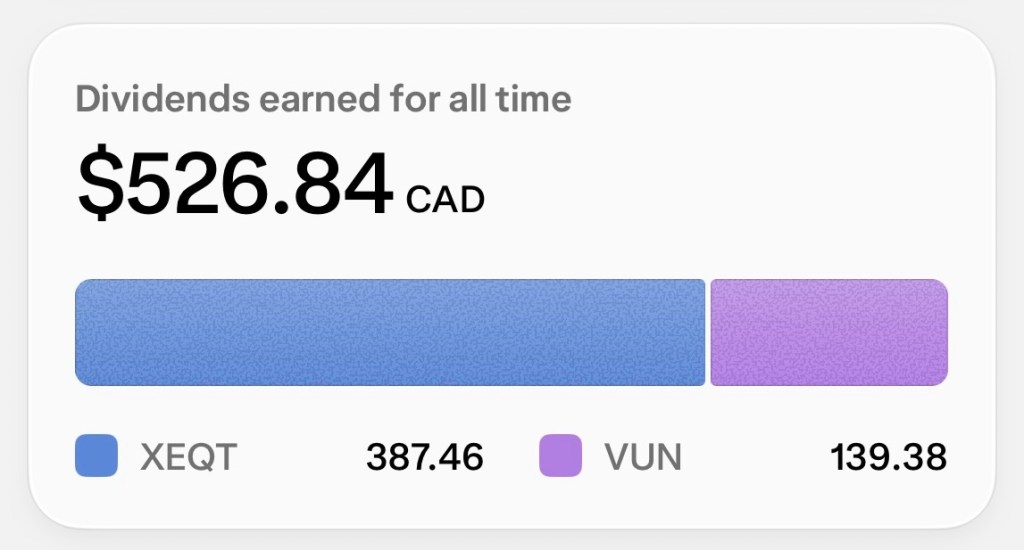
Ideally, we will sell shares and withdraw the money pag retired na kami. Pero since nagkaron kami ng goal na bumili ng bahay, we cashed out parts of it. Nung nakarecover na kami sa biglang taas ng monthly expenses (finally), balik lang kami ulit sa pagbili ng shares every payday. It doesn’t matter how big or small the amount is, what matters is that you start. Today.
Disclaimer: kung bigla mang bumagsak ang stock market, it’s going to be a global crisis and we’ll probably have much bigger issues to worry about than just our stock portfolios 😅
Closing time 🎶
As you may well notice, I am very passionate about this topic. It gives me stress and joy at the same time, but mostly joy. Whenever someone asks me about budgeting, investing, or anything personal finance, I try to restrain myself from being overly enthusiastic for fear of overwhelming the person. But sometimes, I can’t help myself, hehe. So if you ever want to cheer me up or brighten my day a little bit, it’s so easy: ask me for money advice 😂
Part 1: Monthly Expenses in Calgary: Our Money System
Part 2: You are here


Leave a Reply